


Why DEBT (also mortgages) must be avoided by all means
real estate becomes illiquid faster than almost anything else in a depression
Why DEBT (also mortgages) must be avoided by all means
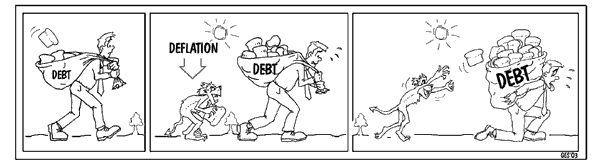
The reason that getting rid of debt is priority #1 is that during deflation, real interest rates will be punishingly high even if nominal rates are low. That is because the real rate (adjusted for changes in the money supply) is the nominal rate minus inflation, which can be positive or negative. During inflationary times, this means the real rate of interest is lower than the nominal rate and can even be negative, as it was during parts of the 1970s and again in the middle of our own decade. People have taken on huge amounts of debt because they were effectively being paid to borrow, but periods of negative real interest rates are a trap. They lure people into too much debt that they may not be able to service if real rates rise even a little. Most people are now thoroughly enmeshed in that trap, as real rates are set to rise substantially.
When inflation is negative (i.e., deflation), the real rate of interest is the nominal rate minus negative inflation. In other words, the real rate is higher than the nominal rate, possibly significantly higher. Even if the nominal rate is zero, the real rate can be high enough to stifle economic activity, as Japan discovered during its long sojourn in the liquidity trap. Standard money supply measures don’t necessarily capture the scope of the problem as they don’t adequately account for ongoing credit destruction, when credit has come to represent such a large percentage of the effective money supply.
The difficulty from the point of view of debtors can be compounded by the risk that nominal interest rates will not stay low for years, as they did in Japan, but may shoot up as the international debt financing model comes under stress. For instance, ongoing bailouts may cause international lenders to balk at buying long-term treasuries for fear of their effect on the dollar's value, even though those bailouts do not increase liquidity because banks hoard it. We are not there yet, but the probability of this scenario rises as we move forward with current policies. The effect would be to send nominal interest rates into the double digits, and real interest rates would be even higher. The chances of servicing existing debt under those circumstances are slim, especially as unemployment rises quickly.
There is no safe level of debt to hold, including mortgages. For those who can't own a home outright, most would be better off selling and renting, as real estate becomes illiquid faster than almost anything else in a depression. By the time you realize that you need to sell because you can no longer pay the mortgage, it may be too late. Renting is essentially paying someone else a fee to take the property price risk for you, which is a very good bet during a real estate crash. It would also allow you to address point #2 – having access to liquidity.
© - The report's contents may be copied, reproduced, or distributed with the explicit written consent of Goldonomic.